


Global Markets Close — September 14, 2026
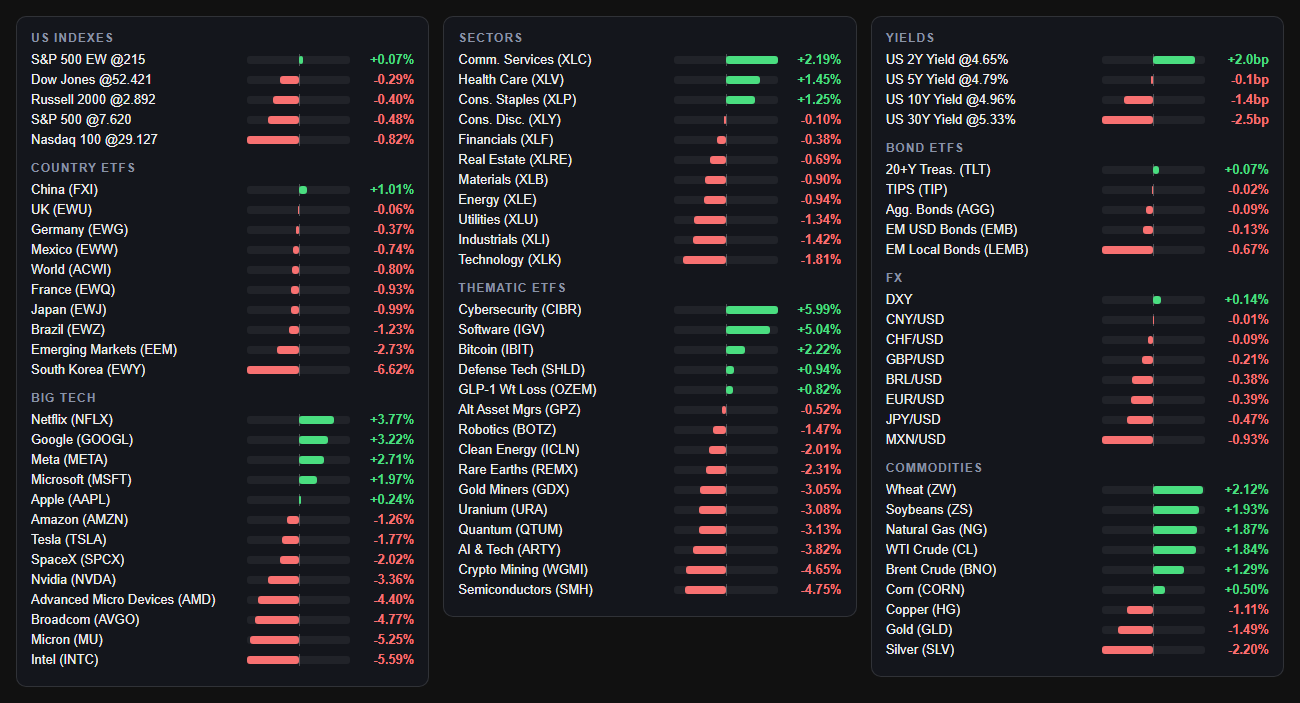
Global AI industry leaders' call to slow development sent chip stocks reeling, with Nvidia (NVDA) -3.36%, AMD (AMD) -4.40%, Micron (MU) -5.25% and the Semiconductors ETF (SMH) -4.75%, dragging the Nasdaq 100 -0.82% and S&P 500 -0.48% lower even as software rotated higher, with Software (IGV) +5.04% and Cybersecurity (CIBR) +5.99%. Oil extended its Middle East-driven surge, with WTI crude +1.84% to $101.89, reviving inflation risk just as traders price a high probability of a Fed rate hike this week. South Korea (EWY) sank -6.62%, leading Emerging Markets (EEM) -2.73% lower as the AI-slowdown warning hit Asian tech hardest.
What Moved the Market
The Nasdaq 100 dropped -0.82%, the S&P 500 fell -0.48% and the Dow slipped -0.29% as chipmakers led losses: Nvidia (NVDA) -3.36%, AMD (AMD) -4.40%, Micron (MU) -5.25%, Broadcom (AVGO) -4.77%, Intel (INTC) -5.59% and the Semiconductors ETF (SMH) -4.75%. — AI industry leaders called for slower AI development today, spooking investors in richly valued chip names most exposed to any pullback in AI capex.
WTI crude jumped +1.84% to $101.89 and Brent (BNO) rose +1.29% to $62.16 on intensifying Middle East supply disruptions, even though Energy (XLE) itself slipped -0.94% on the day. — Tightening flows through key shipping chokepoints and Saudi pipeline damage are reviving inflation risk right as traders price a high probability of a Fed rate hike this week.
Software (IGV) surged +5.04% and Cybersecurity (CIBR) jumped +5.99%, led by CrowdStrike and Palo Alto Networks, decoupling sharply from the day's chip-stock selloff. — Investors rotated within tech, favoring software's recurring-revenue model over semiconductor names seen as most exposed to any AI-spending slowdown.
Comm. Services (XLC) led all sectors at +2.19%, followed by Health Care (XLV) +1.45% and Cons. Staples (XLP) +1.25%; Technology (XLK) lagged at -1.81%, with Industrials (XLI) -1.42% and Utilities (XLU) -1.34% also down. — Strength in Meta (META) +2.71%, Alphabet (GOOGL) +3.22% and Netflix (NFLX) +3.77% pulled Comm. Services higher and defensives held up, while AI-exposed Technology and rate-sensitive Utilities and Real Estate (XLRE) -0.69% sold off ahead of an expected Fed hike.
South Korea (EWY) tumbled -6.62%, dragging Emerging Markets (EEM) -2.73% while Japan (EWJ) fell -0.99%. — Asian AI-linked stocks bore the brunt of today's global slowdown warnings, with a Bank of Japan hike looming alongside the Fed's.
Chart of the Day
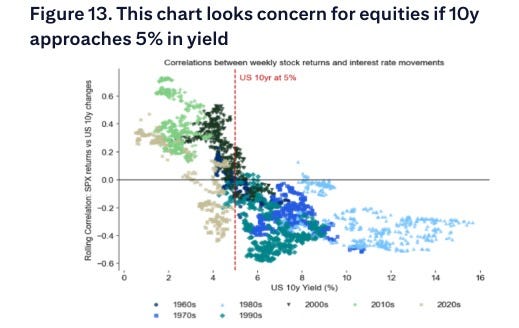
Chart 13: This chart looks concern for equities if 10% yield approaches 6% in weekly stock returns and 10% yield approaches 6% in weekly stock returns
The chart shows the relationship between weekly stock returns and the yield on 10-year Treasury bonds. There is a noticeable trend where as the yield on 10-year Treasury bonds approaches 6%, the weekly stock returns tend to decrease. This suggests that investors may be more cautious when the yield on 10-year Treasury bonds is high, potentially leading to lower stock prices. This chart could be used to support an investment thesis that suggests caution in the stock market when the yield on 10-year Treasury bonds is high.
Source: Citi — Global Macro Strategy - Views and Trade Ideas - 5 bearish worries we are more sanguine on and 2 gamechangers
Paying subscribers get The Edge below — full report breakdowns, rating-change clusters, and today's portfolio-implications read.
The Edge
Today's most important themes: Fed hike consensus meets oil and AI risk
TL;DR
🔴 Fed hike near-lock-in — Citi, Goldman, JPMorgan, UBS and Morgan Stanley now all expect a 25bp hike to 3.75%-4.00% this week, with markets pricing ~90% odds; Citi and Vital Knowledge both frame it as one-and-done, not a new tightening cycle.
🔴 Semis sell, software rallies — today's tape confirms the rotation: SMH -4.75%, INTC -5.59%, MU -5.25%, AVGO -4.77% while IGV gains 5.04% and CIBR jumps 5.99%. Goldman's Chart of the Day says the 3-month vs 12-month momentum gap just hit its widest in five years as AI exposure decouples from the momentum factor.
🟡 Oil-driven stagflation risk — WTI is up 1.84% to $101.89 today; Gavekal and Citadel Securities warn suspected Saudi/Russian refinery and pipeline attacks are reviving stagflation odds, while Vital Knowledge and World Gold Council cite their own intraday Brent prints above $100-$108.
🔴 Long yields near 5% — the actual 10-year sits at 4.96% (-1.4bps) and the 30-year at 5.33% today. Goldman lifts its year-end 2026 10-year forecast to 4.75%, and JPMorgan argues the S&P 500 can absorb yields near 6% given 28%/21% projected 2026/27 EPS growth.
⚪ AI capex debate widens — Citi says AI labs' calls to self-pace frontier development are both a sincere safety move and an attempt to shape regulation before it's forced on them, while Goldman's Communacopia takeaways argue capex stays elevated through 2027 as internet leaders pivot from experiments to measurable ROI.
