


Global Markets Close — August 21, 2026
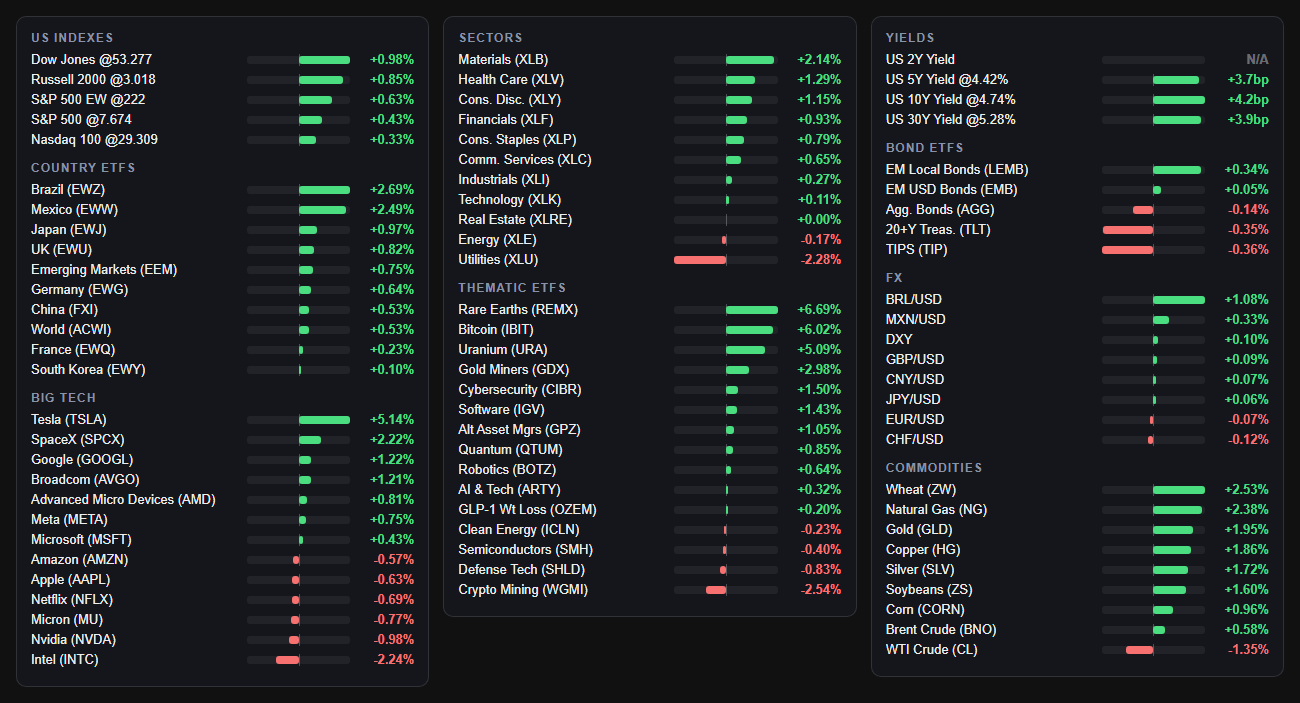
Wall Street capped a turbulent week with broad gains, led by the Dow (+0.98%), S&P 500 (+0.43%), Nasdaq 100 (+0.33%) and Russell 2000 (+0.85%), as Tesla (TSLA) surged +5.14% after Nevada cleared it for robotaxi deployment. Treasury yields kept climbing regardless, with the 10Y reaching 4.74% (+4.2bps) as breakeven inflation hit a two-month high on worries over Bessent's bond-buyback push, sending investors into gold (GLD +1.95%), Bitcoin (IBIT +6.02%) and rare earths (REMX +6.69%) as fiscal-credibility hedges.
What Moved the Market
Tesla (TSLA) jumped +5.14% after Nevada cleared the company to deploy thousands of robotaxis in Las Vegas, adding to its planned Cybercab launch in Austin; the Dow led major averages +0.98%, with the S&P 500 up +0.43% and the Nasdaq 100 +0.33%. — A state regulatory green light expands Tesla's autonomous-ride ambitions beyond Texas and gave the broad market a mega-cap lift heading into the weekend.
The 10Y Treasury yield rose to 4.74% (+4.2bps), the 30Y climbed to 5.28% (+3.9bps) and the 5Y advanced to 4.42% (+3.7bps) as breakeven inflation rates hit their highest level in more than two months. — Treasury Secretary Bessent's buyback push aimed at calming the bond market is instead stoking inflation worries, keeping long-end yields elevated.
Materials (XLB +2.14%) and Health Care (XLV +1.29%) led all 11 S&P sectors, followed by Consumer Discretionary (XLY +1.15%), while Utilities (XLU -2.28%) was the day's biggest laggard alongside a flat Real Estate (XLRE +0.00%) and Energy (XLE -0.17%). — Rate-sensitive Utilities sold off hard as Treasury yields climbed across the curve, while cyclical, commodity-linked Materials caught a bid alongside broad gains in metals.
Gold (GLD) rallied +1.95%, Silver (SLV) +1.72%, Gold Miners (GDX) +2.98% and Bitcoin (IBIT) +6.02%, extending a milestone run in gold prices. — Investors are piling into hard-asset hedges as fiscal-credibility concerns around Treasury market intervention keep percolating.
Rare Earths (REMX) spiked +6.69% and Uranium (URA) jumped +5.09%, while commodity-linked Brazil (EWZ) +2.69% and Mexico (EWW) +2.49% outperformed as copper (+1.86%) and wheat (+2.53%) also gained. — Broad commodity strength is lifting resource-heavy emerging markets even as developed-market bond yields climb.
The Week Ahead
Wednesday, Aug 26
Earnings:
NVIDIA (NVDA) reports after the close. AI capex bellwether (EPS $2.086)
Salesforce (CRM) reports. Cloud software demand gauge (EPS $3.28)
Crowdstrike (CRWD) reports. Cybersecurity spending indicator (EPS $0.285)
Thursday, Aug 27
Earnings:
Marvell Technology (MRVL) reports. Data infrastructure and AI networking (EPS $0.933)
Workday (WDAY) reports. Enterprise software and cloud trends (EPS $2.614)
Also this week
Econ: Global Flash PMIs - early read on growth momentum
Econ: UK, Canada, and Japan CPI prints - inflation trends
Econ: Chinese monthly data and UK, Australia, Eurozone wages - global reflation check
Econ: Beijing World Robot Conference - tech policy and innovation signals
Event: Lagarde speech - ECB stance on inflation and policy
Chart of the Day
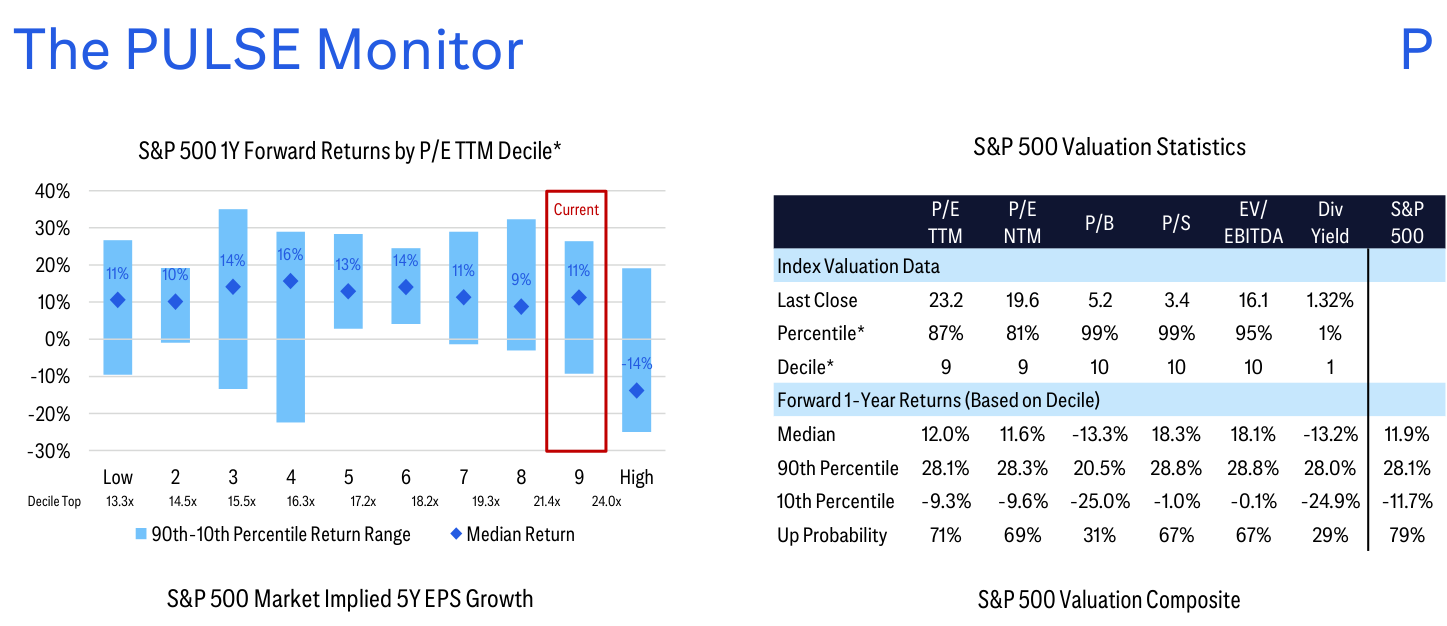
The left panel shows the distribution of S&P 500 1-year forward returns across P/E TTM deciles, with blue bars representing the 90th-to-10th percentile return range and diamond markers showing median returns; the current market sits in Decile 9 (P/E TTM up to 21.4x), highlighted in red. At Decile 9, the median 1-year forward return is 11%, but the range spans roughly -14% to +31%, reflecting high dispersion at elevated valuations. The right-panel table reinforces the stretched picture: the S&P 500's current P/E TTM of 23.2x sits at the 87th percentile (Decile 9), while P/B (5.2x), P/S (3.4x), and EV/EBITDA (16.1x) are all at the 99th/95th percentile — Decile 10 — implying median forward returns of -13.3% and 18.1% on those metrics respectively, with up-probabilities of only 29-31%. The composite S&P 500 signal is modestly constructive (79% up probability, 11.9% median return), but the extreme readings on price-to-book and price-to-sales argue for above-average left-tail risk.
Source: Citi — PULSE Monitor Summer Conundrums
Paying subscribers get full access to The Edge below:
The Edge
Today's most important themes: Buyback relief doubted as valuations stretch
TL;DR
🔴 Treasury buybacks — Citi's GAA closed its US duration underweight after Treasury signaled defending 5.30% on 30yr via $16bn/quarter buybacks, but Goldman and Nomura argue the doubled $4bn/operation pace won't durably cap yields; the 10Y still rose 4.2bps to 4.74% today.
🔴 Citi's dovish pivot — Citi lifted its S&P 500 year-end target to 8100 on $365/$400 2026/27 EPS, raised EURUSD to 1.1750, and initiated a long gold position, reading the Treasury's back-end buyback defense as reducing fixed-income vol and favoring debasement trades.
🟡 Valuation risk — JPM's Hunter draws a 1999-2000 analog as semis, EM equities, and industrial metals fail to confirm index highs, while UBS's Turbu-lens hit its first +1 extreme since Dec 2024 and Citi flags 99th-percentile P/B/P/S heading into Jackson Hole and the Sep FOMC.
🔴 Gold — Goldman warns GLD call-put open interest near 2.5M contracts, versus the 1.3M it assumed in its $4,900/oz year-end forecast, creates a dealer-hedging amplifier for both upside and downside; gold actually rose 1.95% today with GDX up 2.98%.
🟡 China — Goldman's tracker shows Q3 GDP tracking near 4% yoy, steel output down 8.7% yoy, and July retail sales up just 0.6%, even as Apollo's chief economist projects China's export-driven trade surplus hitting $3.5T by 2027, nearly 3x the 2007 peak.
⚪ Walmart — JPMorgan cut its WMT price target to $125 from $137 and UBS cut to $130 from $141, but both reiterated Overweight/Buy after the 2Q comp miss, calling the selloff overdone as ecommerce and marketplace growth offset slowing core stores.
Highlighted Sell-Side Reports Today (2 reports)
Citi — PULSE Monitor Summer Conundrums
Strategas — Modest Trim to Equities, Adding Fixed Income Duration & Real Asset Exposure
